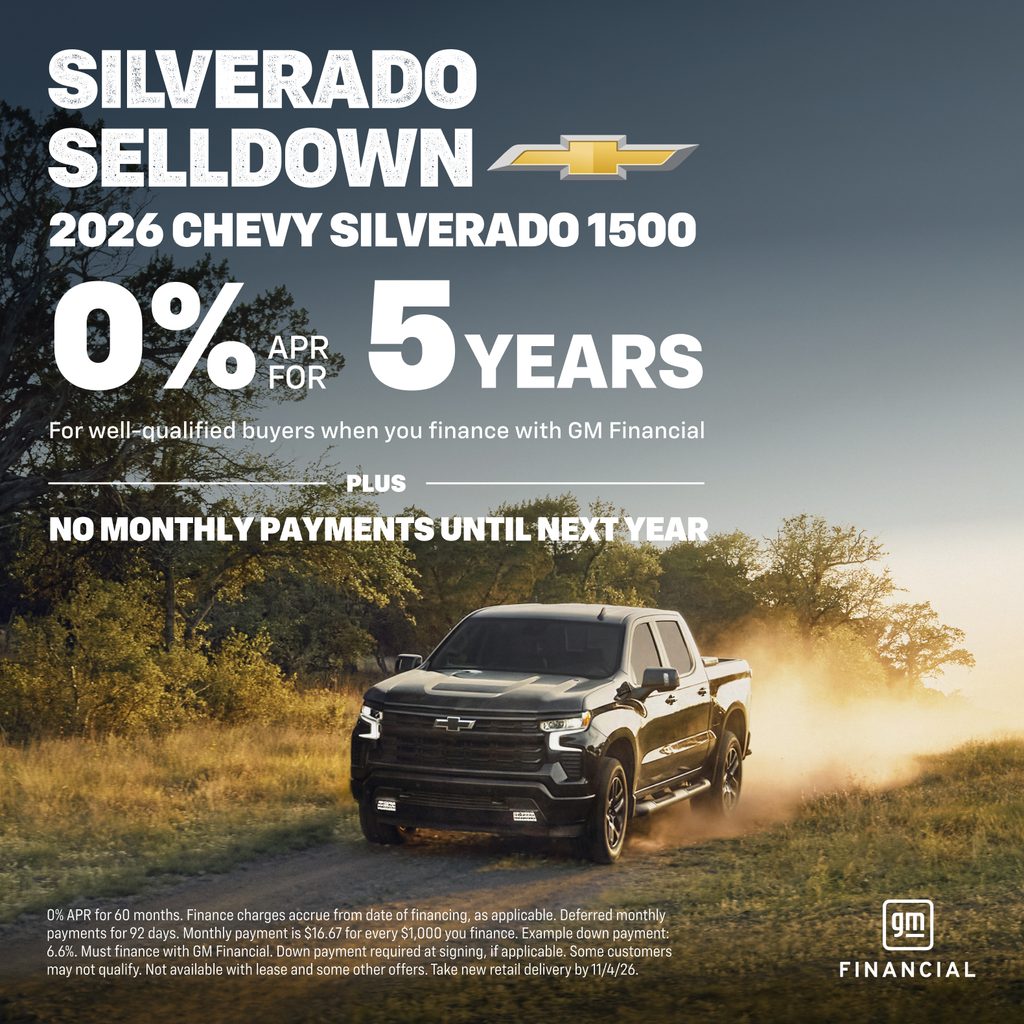
When shopping for a new Chevrolet or GMC, you’ve probably seen advertisements offering 0% APR financing, cash rebates, or special manufacturer incentives.
Both can make buying a new vehicle more affordable. But which offer actually saves you more money?
The answer depends on the vehicle’s price, the size of the rebate, your available interest rate, and how long you plan to finance your purchase.
For car shoppers around Harrisburg and Central Pennsylvania, understanding the difference between 0% APR vs. cash rebates can help you make a more informed decision before signing your next auto loan.
Let’s break down how these incentives work, compare real numbers, and explain when each option may be the better deal.
What Does 0% APR Financing Mean?
0% APR financing means you’re borrowing money without paying interest or finance charges on the qualifying loan.
For example, imagine purchasing a new Chevrolet with an amount financed of $30,000.
With 0% APR financing for 60 months:
- Amount financed: $30,000
- Interest rate: 0%
- Loan term: 60 months
- Monthly payment: $500
- Total loan payments: $30,000
In this simplified example, you pay back exactly what you borrowed.
With a traditional auto loan, interest increases the total amount you repay.
That’s what makes zero-percent financing attractive, particularly when financing a substantial portion of a new vehicle’s purchase price.
However, 0% APR offers are typically available only on select vehicles, for specific loan terms, and to qualified buyers.
What Is a Cash Rebate on a New Car?
A cash rebate, sometimes called customer cash or a manufacturer cash allowance, is an incentive that reduces the effective purchase price of a qualifying vehicle.
For example, imagine a Chevrolet SUV with a negotiated selling price of $35,000.
If a qualifying $3,000 rebate applies, the effective vehicle price becomes $32,000 before applicable taxes, fees, and other transaction adjustments.
Unlike 0% financing, a cash rebate directly reduces the vehicle’s purchase cost.
But there’s an important distinction.
If you finance the remaining balance at a standard interest rate, you’ll still pay interest over the life of the loan.
That’s why a larger upfront rebate doesn’t automatically mean a lower overall cost.
0% APR vs. Cash Rebate: A Real Payment Comparison
Let’s compare two hypothetical offers on the same $35,000 vehicle.
Option A: 0% APR for 60 Months
- Vehicle price: $35,000
- Cash rebate: $0
- Amount financed: $35,000
- APR: 0%
- Term: 60 months
- Monthly payment: $583.33
- Total loan payments: $35,000
Option B: $3,000 Cash Rebate With 6% APR Financing
- Vehicle price: $35,000
- Cash rebate: $3,000
- Amount financed: $32,000
- APR: 6%
- Term: 60 months
- Monthly payment: approximately $618.65
- Total loan payments: approximately $37,119
| Comparison | 0% APR | $3,000 Rebate |
|---|---|---|
| Amount financed | $35,000 | $32,000 |
| APR | 0% | 6% |
| Loan term | 60 months | 60 months |
| Monthly payment | $583.33 | $618.65 |
| Total loan payments | $35,000 | $37,119 |
In this example, choosing 0% APR saves approximately $2,119 over the full loan term.
Even though the rebate reduces the amount financed by $3,000, the interest charged on the remaining balance more than offsets those savings.
These figures are illustrative, not current dealership offers. They assume no down payment, trade-in, taxes, fees, or additional financed products, and assume the quoted APR reflects the stated interest rate without separate finance charges.
When Is 0% APR Financing the Better Deal?
Zero-percent financing can be especially attractive when you’re financing a larger amount over several years.
Consider a few situations.
You’re Financing Most of the Vehicle’s Price
The more money you borrow, the more interest you could potentially pay with a conventional auto loan.
Eliminating interest can create substantial savings over the life of the loan.
The Available Cash Rebate Is Relatively Small
If you’re choosing between 0% APR and a modest rebate, the interest savings may easily exceed the rebate’s value.
You Plan to Keep the Loan for Its Full Term
If you expect to make every scheduled payment over the entire financing period, comparing total loan payments provides a useful picture of the cost difference.
The Monthly Payment Fits Your Budget
A 0% APR offer isn’t automatically the best choice if it requires a shorter loan term with payments you can’t comfortably afford.
Always consider both affordability and total cost.
When Is a Cash Rebate the Better Deal?
A cash rebate can sometimes provide greater financial value than promotional financing.
You’re Paying Cash for the Vehicle
If you aren’t financing your purchase, a 0% APR loan offers no interest savings relative to paying cash.
A qualifying cash rebate may therefore be more useful.
You Have a Large Down Payment
A substantial down payment reduces the amount you need to finance.
When you’re borrowing less money, the total interest savings from a promotional rate may also be smaller.
You Qualify for a Competitive Interest Rate
If you can obtain a low APR through a bank, credit union, or another lender, combining that financing with an eligible cash rebate may produce a lower total cost.
The Rebate Is Large Enough to Offset Interest
The bigger the rebate, the more compelling the cash incentive may become.
A useful way to think about the decision is:
Does the rebate exceed the additional financing cost of choosing the standard-rate loan?
If it does, the rebate may be the better financial choice, assuming the other transaction terms are comparable.
Can You Combine 0% APR Financing With a Cash Rebate?
Sometimes, but not always.
Certain manufacturer incentives can be combined, while others are mutually exclusive.
For example, a promotional financing offer might require you to give up a specific customer cash incentive.
Other offers may allow additional qualifying incentives, depending on the program.
This is why it’s important to review the actual Chevrolet or GMC incentive details for the vehicle you’re considering.
Don’t assume that every advertised discount can be combined with every advertised financing rate.
Ask which incentives are available together and request a comparison of the eligible offers.
Does 0% APR Mean No Down Payment?
Not necessarily.
A 0% APR offer means qualifying financing carries no interest or finance charges. It doesn’t automatically guarantee that you can finance the entire vehicle purchase without putting money down.
Your required down payment may depend on your credit profile, the vehicle, the amount financed, lender guidelines, and the promotional program.
Taxes, registration, title fees, and other transaction costs also need to be accounted for.
Before purchasing, review the full amount due at signing and the total amount financed.
Who Qualifies for 0% APR Financing?
Promotional financing programs generally have eligibility requirements.
These may include credit qualifications, eligible models, specific loan terms, and financing through a designated lender.
Buyers with stronger credit profiles are typically more likely to qualify for the lowest advertised financing rates.
However, qualification isn’t determined by a single universal credit-score threshold.
The requirements depend on the specific offer and lender.
If you don’t qualify for 0% APR, that doesn’t necessarily mean you can’t finance the vehicle.
You may still have other financing options available.
Does a Longer Loan Term Make a Better Deal?
Not automatically.
A longer loan term can lower your monthly payment by spreading the balance over more months.
But when interest is charged, a longer repayment period can increase your total borrowing cost.
For example, a 72-month loan may offer a more manageable monthly payment than a 48-month loan, but the total interest paid may be greater.
That’s why comparing only monthly payments can be misleading.
When evaluating financing offers, look at the APR, loan term, amount financed, monthly payment, and total of payments.
What If You Plan to Pay Off Your Car Early?
Your expected payoff timeline can influence the comparison.
If you choose a standard-rate loan with a cash rebate but pay off the balance significantly earlier than scheduled, you may pay less interest than the original full-term estimate.
That could make the rebate more attractive.
However, the outcome depends on the loan’s actual terms, how interest is calculated, and whether any prepayment restrictions or charges apply.
Before making a decision based on early repayment, review the financing agreement carefully.
Does Your Trade-In Affect the Decision?
Yes.
Your current vehicle’s trade-in value can change the amount you need to finance.
If your vehicle has positive equity, that equity may reduce the amount financed on your next purchase.
If you owe more than your vehicle is worth, you have negative equity.
Negative equity may need to be paid separately or, subject to lender approval, incorporated into the next vehicle’s financing.
Either situation can influence whether 0% APR or a cash rebate produces the better overall result.
The most useful comparison includes your trade value, current payoff, down payment, eligible incentives, and financing terms.
How to Compare Chevrolet and GMC Financing Offers
Before choosing between promotional financing and cash incentives, ask for two complete purchase scenarios.
Scenario A: Promotional APR Financing
Request the vehicle selling price, applicable incentives, amount financed, APR, loan term, monthly payment, and total of payments.
Scenario B: Cash Rebate With Alternative Financing
Request the same information, including the eligible rebate and the actual alternative APR available to you.
Make sure both scenarios use consistent assumptions for your down payment, trade-in, and optional products.
Then compare the total amount you’ll pay, including any upfront costs.
The better offer is the one that meets your financial priorities and produces the most favorable overall terms.
Find Chevrolet and GMC Financing Offers Near Harrisburg, PA
If you’re shopping for a new Chevrolet or GMC near Harrisburg, comparing available incentives can be just as important as comparing vehicles.
At My Car Chevrolet GMC in Millersburg, Pennsylvania, our team can help you explore available manufacturer incentives, financing programs, and vehicle options.
Whether you’re considering a Chevrolet Silverado, Colorado, Trax, Equinox, Traverse, GMC Sierra, Terrain, or Acadia, the best available offers can vary by model and timing.
We’re located at 640 State Street, Millersburg, PA 17061, serving drivers from Harrisburg, Halifax, Elizabethville, Lykens, Camp Hill, Selinsgrove, Sunbury, and surrounding Central Pennsylvania communities.
Explore our current Chevrolet and GMC inventory, review available specials, or contact our finance team to discuss your options.
Final Verdict: Is 0% APR Better Than a Cash Rebate?
Neither incentive is always the better deal.
Zero-percent financing can save thousands of dollars in interest, especially when financing a larger amount over several years.
Cash rebates can offer greater savings when the incentive is substantial, the alternative financing rate is competitive, or you’re paying cash.
The most important thing is to compare the entire transaction.
Don’t choose a deal solely because it advertises a large rebate or an attractive monthly payment.
At My Car Chevrolet GMC, you can explore available Chevrolet and GMC offers and compare your options before deciding which vehicle and financing structure fit your needs.
Frequently Asked Questions About 0% APR and Cash Rebates
Is 0% APR better than a cash rebate?
It depends on the rebate amount, alternative financing rate, loan term, and amount financed. Zero-percent financing may save more in interest, while a large cash rebate combined with a competitive rate may provide greater total savings.
Is 0% APR financing really interest-free?
A genuine 0% APR auto loan has no interest or finance charges on the qualifying financing agreement. However, you still owe the financed principal, and other vehicle purchase costs may apply.
Can I get 0% APR and a cash rebate together?
Some incentives can be combined, but others cannot. Eligibility depends on the specific manufacturer program, vehicle, and financing terms.
What credit score do I need for 0% APR?
There is no single universal score requirement. Promotional financing typically requires strong credit, and qualification is determined by the lender and the specific offer.
Is a cash rebate better if I pay cash?
Often, a cash rebate is more valuable to a cash buyer because there is no financing interest to save. However, the available incentives and purchase terms should still be compared.
Does 0% APR mean no monthly payments?
No. A 0% APR loan still requires repayment of the amount financed. The zero-percent rate means qualifying financing does not accrue interest.
Can I pay off a 0% APR loan early?
Early repayment depends on the terms of the financing agreement. Review your contract for any applicable restrictions or charges.
Where can I compare Chevrolet and GMC financing specials near Harrisburg?
My Car Chevrolet GMC in Millersburg, PA, can help shoppers review available Chevrolet and GMC financing programs and eligible manufacturer incentives.
Connect with us
